

Dear Fellow Expat:
It’s the beginning of the month as the Polar Vortex rocks the United States.
It’s cold… You walk to your mailbox.
There, you find and open your monthly utility bill.
The number glows back at you…
The electricity bill is higher than last month's.
That makes no sense… does it?
After all… you've shut off lights, dialed back the thermostat, cut showers short...
But that doesn’t change anything.
Despite your efforts, the monthly bill keeps climbing.
You scratch your head. What the hell is going on here?
You live modestly and budget carefully. Yet the bill grows.
You start to get suspicious...
Maybe you even walk outside to check your meter. You stare as the numbers tick higher on the machine, wondering if someone’s siphoning electricity…
Something’s off.
You’re not paranoid… just paying attention.
Your habits don’t fully measure the costs you face.
It’s about infrastructure demands you never signed up for.
And one of the newest and fastest-growing sources of that demand?
Artificial Intelligence.
In 2024, U.S. data centers consumed roughly 183 terawatt-hours (TWh) of electricity... already more than 4% of the nation’s total power consumption.
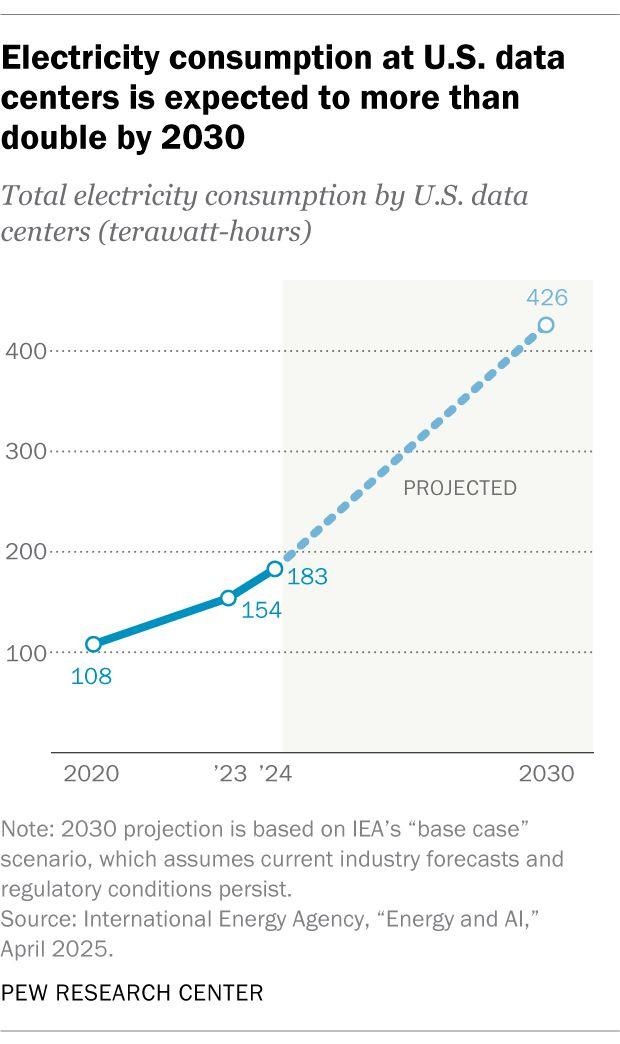
Projections show this won’t stay small. It’ll just keep rising…
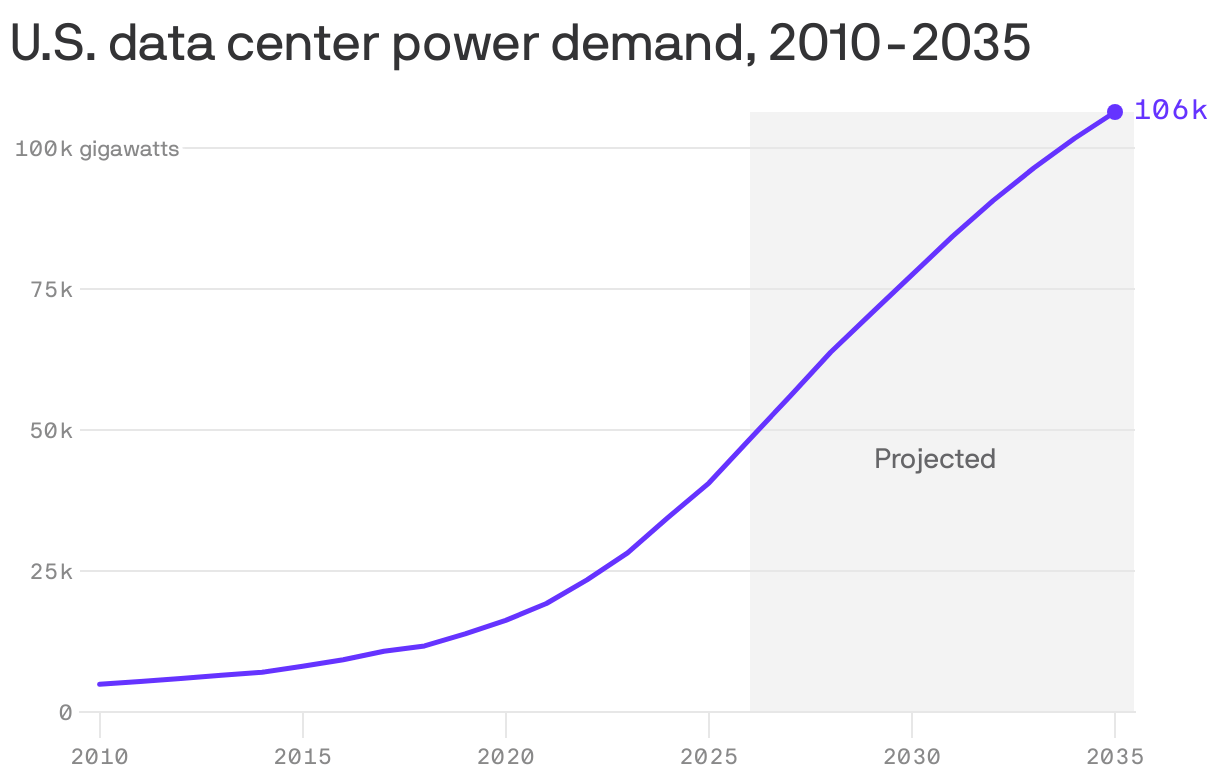
A recent forecast from BloombergNEF estimates U.S. data-center power demand could soar to 106 K gigawatts (GW) by 2035.
Other estimates... including from the U.S. Department of Energy... suggest that data centers could consume between 6.7% and 12% of U.S. electricity by 2028 under certain growth scenarios, with usage climbing to 325-580 TWh per year.
These are projections, not certainties. But the trajectory is clear.
One sector…. It’s just a fraction of the grid today.
But likely to become a major, structural share within a few years.
That’s how they’re taking.
Not through a single headline.
That’s how demand compounds. It doesn’t happen through a single headline, but through steady expansion… and an electricity bill that, over time, lands on you.
What’s Beneath the Noise
Publicly, tech companies and industry boosters talk about “innovation,” “efficiency,” “cloud,” “AI,” and “sustainability.”
It’s all a good game…
It’s the kind of language that lands in quarterly reports, investor decks, and press releases.
But behind all that bullshit lies our problem…
Powering these massive data centers is a raw energy consumption monster... and an enormous demand and strain on infrastructure.
Data-center energy use isn’t limited to compute.
It also includes cooling, redundancy, storage, and 24/7 uptime.
In many facilities, cooling all those machines can consume as much power as the servers themselves…
That multiplier effect boosts demand well beyond what the headline usage numbers suggest.
Then you have the clustering impact that hits pockets of America.
Many of these centers cluster in certain regions... They do so because these areas have pre-existing fossil fuel pipelines and infrastructure...
As in… there’s already power there…
Quickly, local grids are strained.
This doesn’t look like a nationwide crisis yet.
But it’s picking up region by region.
What’s beneath the hype is demand... and demand needs supply.
And supply has a chokepoint…
The energy infrastructure.
We’re talking natural gas pipelines, transmission lines, storage... the hidden plumbing of the digital economy.
And policy hasn’t caught up to the infrastructure math.
How “Power” Really Works
I want to talk about the incentive layer... the world nobody writes about in press releases or all these glowing financial media headlines.
On one side sit the tech giants… Amazon, Meta, Alphabet (Google), etc...
They’re cash-rich. They have trillions in capital.
They lease or build vast data-center campuses.
They negotiate favorable tax breaks, subsidies, and state-level incentives.
They lobby non-stop and get to write the damn regulations when it’s time to start thinking about the infrastructure to accommodate… them…
Their expansion is ravenous. This is a post-2008 problem that never got fixed.
On the other side are utilities, grid operators, pipeline companies, and gas suppliers. They see skyrocketing demand.
They need to lay more pipe, build more compressor stations, upgrade transmission lines, expand storage, and plan for 24/7 power delivery.
Those are massive capital expenditures.
But the catch… load generators (data centers) often dodge direct costs.
Sure, they’ll pay for electricity use. They sign power-purchase agreements.
But they seldom pay for the full network upgrade that makes all that electricity possible.
Instead, the costs for new pipelines and transmission lines... get socialized.
Households, renters, small businesses, and local communities will pay…
Shocking right?
Through their bills, rates, and taxes… But it’s not just a financial cost…
They’ll also pay through deferred maintenance or slow upgrade cycles that just make the grid weaker.
In states with ongoing data-center booms... places like Virginia, Texas, Georgia, parts of the Midwest... regulators and utilities are already warning that rate hikes are inevitable if new demand materializes.
Capacity-market costs jump. Infrastructure upgrades stack up. And the burden lands on the people who never signed up for GPUs or AI-training jobs.
This isn’t a conspiracy.
It’s just how incentives work.
AI data centers create demand, the utilities build capacity, and rate-payers absorb the cost.
The architecture and system do what they’re built to do.
The Everyday Hustle Gets More Expensive
These costs show up in lives, in paychecks, in kitchens, not in boardrooms.
Families in regions near data-center expansion... Maryland, Virginia, Ohio, and parts of the South see their electricity bills climb even if they reduce their use.
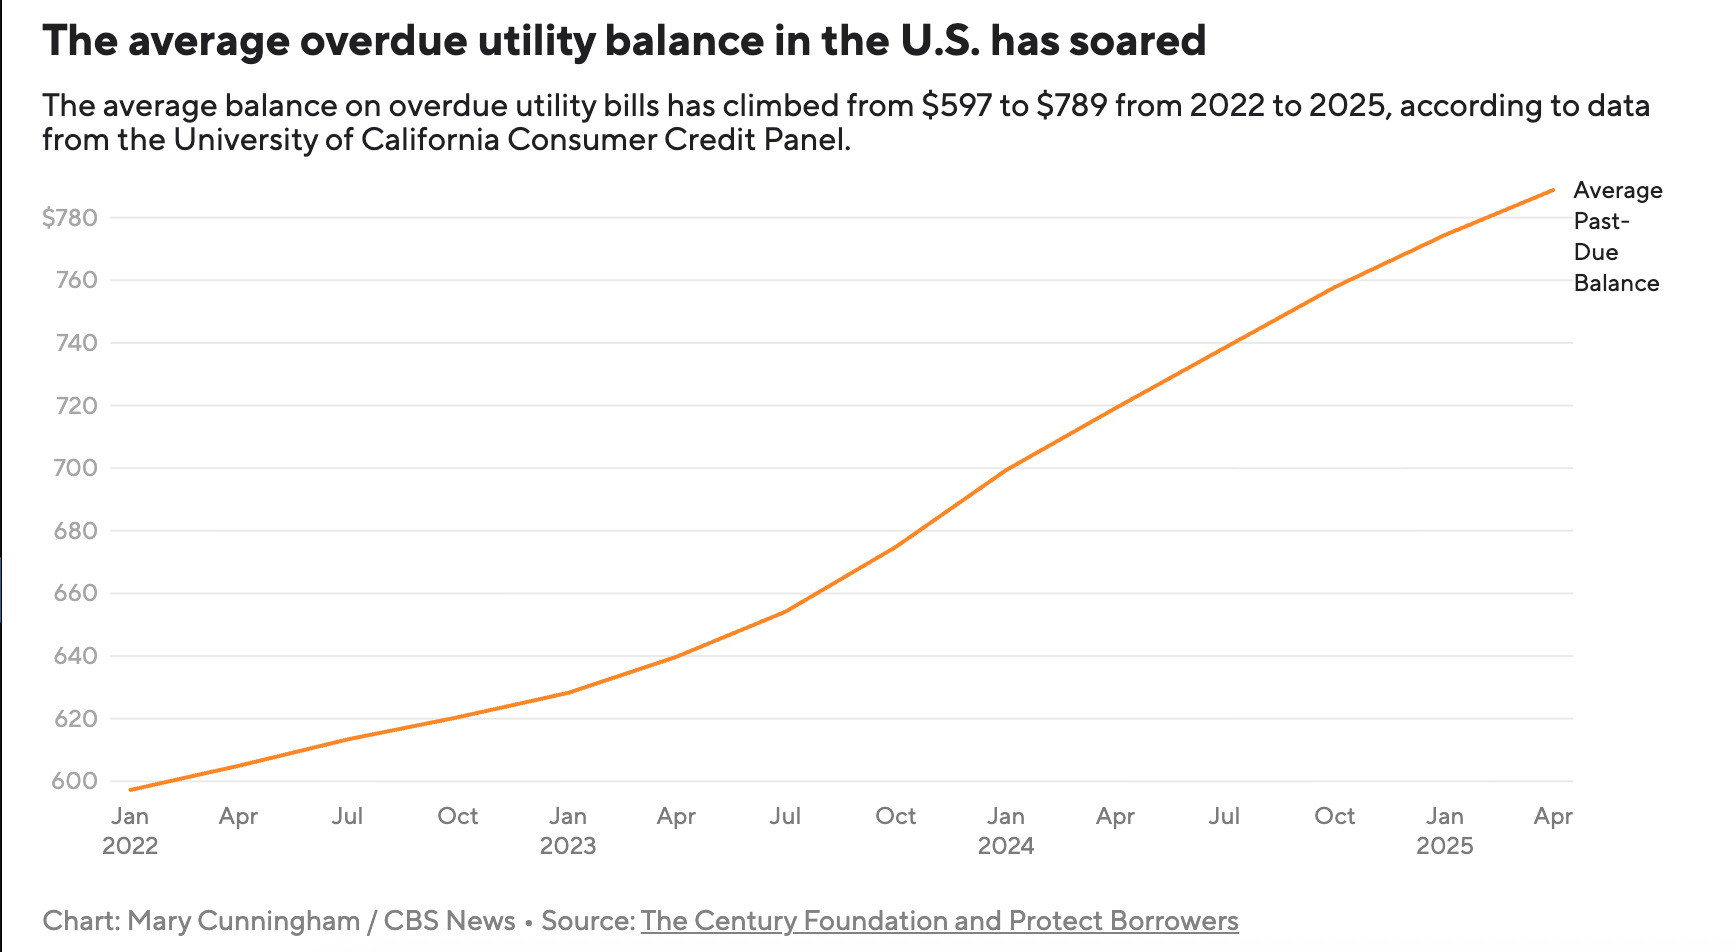
The average overdue utility balance continues to surge. It’s up more than 32% from 2022 to 2025. And these sorts of figures never go down…
Is this entirely because of data centers?
Probably not.
Bills rise for many reasons: fuel costs, infrastructure upgrades, inflation, and weather. But the pattern of rising demand and socialized cost is real.
And it compounds.
Other people and businesses pay through higher rents, never-ending utility surcharges, or broader inflation.
And when infrastructure costs go up, landlords pass them along.
That fee is likely included in the rent.
For people who live paycheck to paycheck... who juggle rent, groceries, credit-card payments, and medical bills... this isn’t a few extra dollars.
It’s nerve-eating stress combined with instability.
And Americans are more and more behind than ever on these costs…
Meanwhile, the companies driving demand... the ones behind data centers, the AI factories, and cloud monopolies... keep expanding, deferring costs, reinvesting capital that would otherwise be tied up in infrastructure… and enjoying all of the new tax benefits (The Big Beautiful Bill is chock full of them…)
In the end… their balance sheets grow, and yours shrinks.
Of course, inflation, infrastructure, fuel prices, and weather... all play a role.
But the structural problem ... where large load-generators drive demand, utilities build capacity, and ordinary people absorb the cost... is not theoretical.
It’s documented. There are receipts all across the country…
And it’s not clear there’s a plan at the local or national level…
Winners and Losers
When you zoom out, the structure becomes clear.
Who wins?
The tech giants get access to cheap (or at least subsidized) energy, scale, and infrastructure without absorbing the full cost.
Energy infrastructure firms... pipeline companies, gas producers, utilities... get paid on volume, capacity, and storage. Their returns grow as demand surges.
Investors in midstream infrastructure win too... these are not flashy unicorns. They are the modern equivalent of toll-road operators. Once built, the path is sticky, often long-term, fee-based, regulatory-captured, and lucrative.
Who Loses?
Households, renters, and working families face higher bills, higher housing costs, and less stability.
Communities... especially those near pipelines, compressor stations, or power plants... may face safety or cost burdens.
This is a structural payoff system.
The architecture of extraction has migrated from labor and manufacturing to infrastructure and energy.
And those who own the pipes... or stand to... will win.
If you see what’s happening... if you feel it... Then the question isn’t just “how do we push back?” The deeper question is “how do we position ourselves so that we’re not merely on defense?”
If electricity demand is surging. If data centers consume 4% today... and maybe 8-12% of the grid under certain scenarios.
If that electricity largely depends on natural gas. If expansion requires more pipelines, more gas flow, more infrastructure... then the chokepoint is obvious.
Energy infrastructure is the chokepoint… especially the pipelines.
In the old world, powerful people controlled trade routes, water, ports, and land.
In our world... the infrastructure of energy, gas, transmission... is just as strategic. If you own that, you own leverage…
The Back Page
This isn’t about sustainability debates or policy reform.
It’s about recognizing where leverage sits and positioning accordingly.
It’s about recognizing that we’ve moved from a world where wealth was generated by production, labor, and manufacturing to a world where it’s generated by control.
I’m talking about control of infrastructure, energy, and associated capital flows.
We’re not playing on equal footing.
The companies controlling the infrastructure... or those who invest in it... have an advantage so baked into the system that you can’t compete by cutting back or conserving.
You compete by owning and putting yourself in the position to own...
You need to be the person in this toll booth...
You need to be the toll collector.
When everyone else pays to stay powered, the one controlling the power gets paid... every single day.
The Sovereign Move
This week, if you want a real leverage and structural advantage... You don’t invest in hype.
You invest in the backbone of infrastructure. The chokepoint that powers everything. The companies that own the pipes, move the gas, control the storage, and manage the energy flow.
That’s why this week’s sovereign moves are so obvious…
Remember, Postcards subscribers will get these stocks and other ideas every single week…
We have one stock recommendation and a handful of steps you can take right away to save money, cut costs, and take back your sovereignty… New readers can unlock this FIRST issue using their one free credit.
So… first…
Invest in Kinder Morgan (KMI).
Why Kinder Morgan?
Because they don’t ride a hype curve. They are the hype curve.
Kinder Morgan operates approximately 66,000 miles of natural-gas pipelines across North America, transporting roughly 40% of the natural gas consumed in the United States.
Its network connects all major U.S. resource basins... the Permian, Haynesville, Marcellus, Bakken, Eagle Ford, Utica... to every major demand center.
The company holds more than 700 billion cubic feet (Bcf) of working gas storage capacity...
Now, Kinder Morgan is structured as a midstream giant…
It owns pipelines, terminals, storage facilities, and processing facilities.
That’s the entire midstream energy chain.
Its revenue model is fee-based, long-term, and largely insulated from the price volatility that hurts the share price and cash flow of oil-and-gas producers.
So, as tech companies race to build data centers that drain more electricity, the segment that benefits structurally and quietly is the one that delivers the gas that powers the plants generating that electricity.
Suppose data-center electricity demand doubles or triples by the end of the decade. In that case, natural gas demand (or any reliable energy mix) must rise.
The grid, at scale, will rely heavily on gas-fired plants… especially given the challenges posed by renewables, load requirements, and 24/7 demand… You can’t shut off a natural gas plant or electricity substation… It has to rattle and hum constantly - something simple but overlooked by politicians….
As demand grows, so does the importance (and hopefully fees) of gas pipelines, storage capacity, and midstream infrastructure.
Owning a slice of Kinder Morgan today is not betting on a speculative “AI bubble.”
It’s betting on the demand growth already baked into the demographics.
This is infrastructure that everyone from households to hyperscalers relies on…
This is a bottleneck that can’t be bypassed without building an entirely new energy network.
So what else are you buying aside from an incredible midstream energy player that Wall Street analysts peg at 15% upside and a healthy 4.2% dividend?
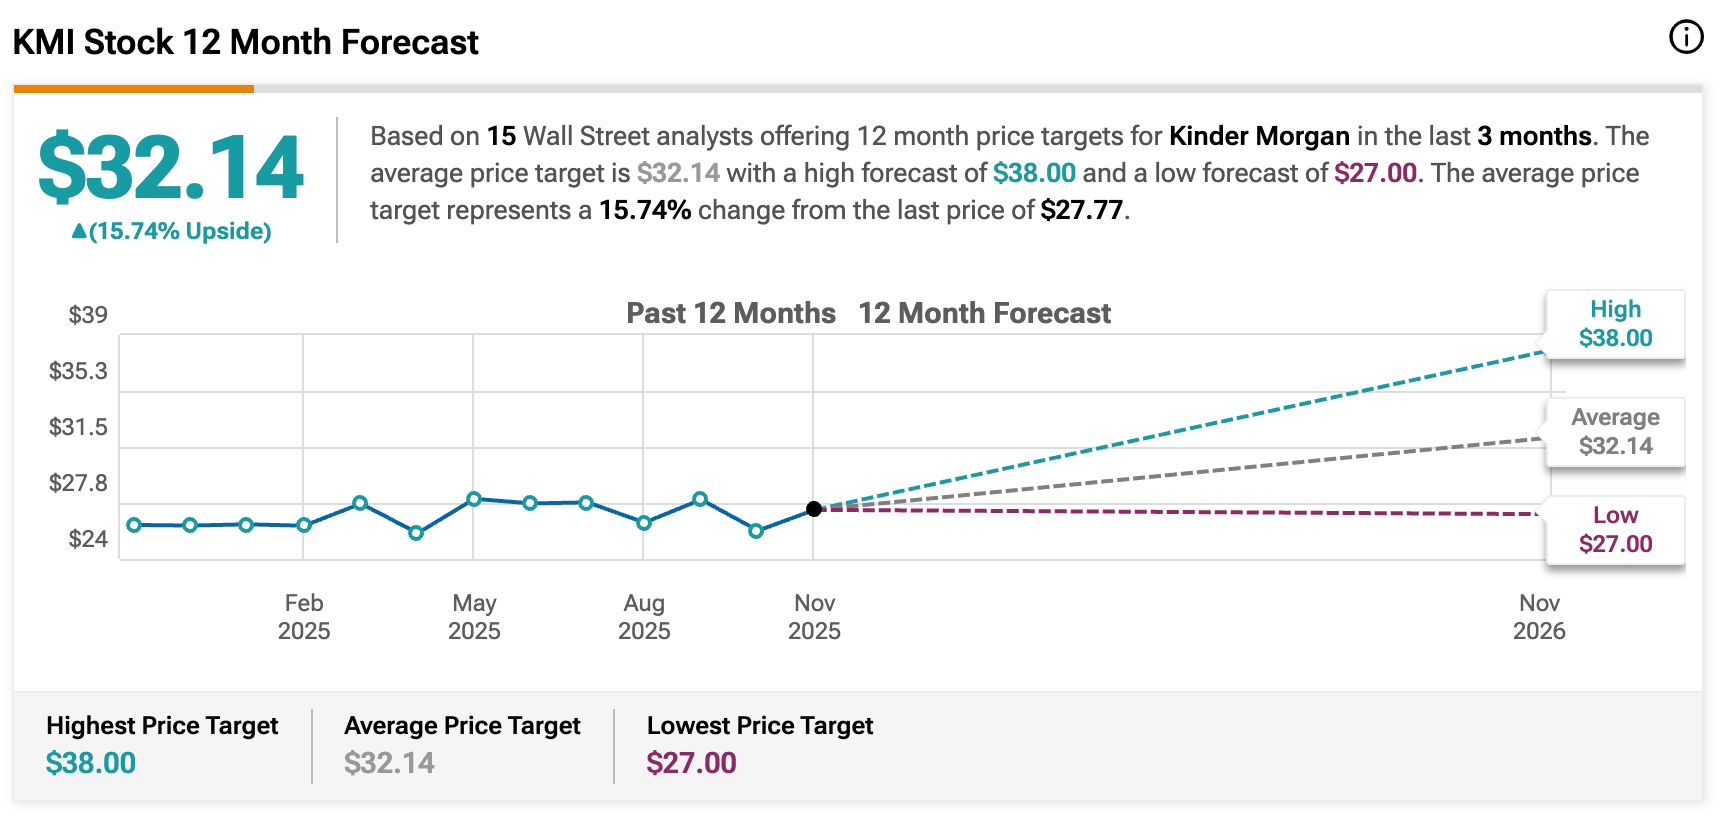
You’re buying leverage and a piece of sovereignty.
But there’s more…
The Household Move
Investment alone is not sovereignty.
Control is also sovereignty.
And not everyone has the resources to buy a stock right now.
We have to free up cash flow so you can participate…
So, I don’t want this letter to be only about making money…
I’ve thought about several non-investment moves to help break the extraction loop, too…
All of them give you back a piece of the leverage the system quietly took. Now you might need to do a little bit of homework on each… but consider…
Switching from variable-rate to fixed-rate electricity plans…
Shifting heavy energy usage to off-peak windows (after 8 pm, overnight charging)…
Adding small, portable solar panels into your mix... not the rooftop mortgage scam, but $120 to $300 units that power routers, laptops, backup lighting… This is something that I do with a lot of the “vampires” in my house.
Build a 90-day liquidity buffer in T-bills so utilities cannot control your timing…
Auditing auto-payments tied to energy... subscription HVAC filters, smart thermostat fees, hidden “grid modernization” charges… This stuff adds up.
Using credit cards that return 3% to 5% cash back on utility payments…
Tracking your kWh usage like a budget item... because you cannot escape a system you do not measure… This is probably the single toughest, yet most impactful, one…
All of these help.
All of them matter.
And they can save you a lot of money… that you could eventually put some into Kinder Morgan stock…
But in the interest of time, I want you to explore one specific move this week…
See if you can lock in a fixed-rate electricity plan for the next twelve months.
If you live in a deregulated electricity state... You can shop for your electricity supplier. That means you can lock in a fixed-rate supply contract...
This is the household version of owning a pipeline.
AI companies get special rates, subsidies, and regulatory preference. You do not.
So your defense is time-shifting the cost structure before the next wave of demand hits the grid.
If you live in a regulated state... You cannot choose your supplier. But you can still change your rate structure. Look into budget billing and time-of-use plans. Consider seasonal smoothing and peak-avoidance pricing.
These are not as powerful as a true fixed-rate contract, but they reduce your exposure to rate spikes when capacity markets tighten.
You might look at this insight and think - this seems like work.
Like I’m giving you a homework assignment. You don’t have to do any of this…
But I assure you that it’s worth it… because the stock market isn’t going to solve all of the problems… and the last thing you want is to have to sell stock just to pay the bill…
As I’ve said, extraction starts small…
It’s death by 1,000 fees… and more are coming.
I’ll circle back with you next week as we discuss the latest with Amazon.
Stay positive,
Garrett Baldwin
Action to Take: Buy Kinder Morgan (KMI) at market price and reinvest the dividends. Be aware that there will be periods of market volatility due to liquidity challenges unrelated to KMI.
KMI remains a long-term position. Buy up to $29.00 per share.
In the future, we’ll also be talking about the Kayne Anderson Energy Infrastructure Fund (KYN), a midstream fund that owns KMI shares alongside a larger, diversified midstream portfolio. In addition, we will discuss ways investors can collect on the pipelines by purchasing bonds with yields similar to those of equity markets but with lower volatility...